New Hampshire
Maserati Insurance
Call Us: 603-766-3733
Picture a Grecale Trofeo pulling out of a Bedford driveway on a February morning. The roads are white with salt brine. Somewhere between Route 101 and the Manchester line, a pickup slides through a stop sign. The repair estimate comes back from a shop that has never torqued a Maserati suspension bolt, and the adjuster wants to pay for parts sourced from a catalog you've never heard of.
That scenario plays out more often than most owners expect. The policy you bought when you drove off the lot decides whether you get factory parts, a certified technician, and a settlement that reflects what the car is worth. It also decides whether you get a check that barely covers the loan payoff.
This guide covers how
Maserati insurance in New Hampshire should be structured. It explains
agreed value settlements, approved repair networks, transport and storage coverage, and how to set limits that match the rest of your financial picture. If you own a Ghibli as a daily driver, a GranTurismo you garage from November to April, or an MC20 that rarely sees rain, the details below matter more than the
premium figure on page one.
The Unique Landscape of Luxury Car Insurance in New Hampshire
New Hampshire is an outlier. It's the only state that doesn't require most drivers to carry auto insurance, though you must prove financial responsibility after an at-fault accident. For a Maserati owner, that rule cuts both ways. Fewer mandates mean more freedom to design coverage, but they also mean more uninsured drivers sharing Route 3 with your car.
The market itself is competitive. In 2026, Insurance Commissioner D.J. Bettencourt noted that New Hampshire drivers benefit from some of the lowest average personal auto premiums in the country, crediting market competition and responsible oversight. Low averages, though, are built around mass-market sedans and SUVs. A Maserati sits outside those actuarial assumptions, and a standard carrier may price it fine while still settling claims as if it were a Camry with a nicer badge.
Consumer protections have also tightened. Regulations issued in September 2026 require insurers to provide a 10-day cure period before terminating a policy for non-payment. That's a real safeguard if an autopay card expires while you're wintering in Naples. Still, don't treat it as a planning tool. A lapse on a six-figure car, even a short one, creates headaches you don't need.
Then there's the climate. Salt, frost heaves, ice dams dropping chunks off garage eaves in Hanover, and gravel on the Kancamagus all create claim patterns that rarely show up on cars garaged in Arizona. A policy written for New Hampshire has to account for all of that.
By: Tod O’Dowd, CIC, CAPI
President of Avery Insurance Agency
Agreed Value vs. Stated Amount: Protecting Your Investment
These three terms sound similar. They produce very different checks after a total loss.
- Actual cash value (ACV): The insurer pays what it decides the car was worth right before the loss, using depreciation tables and comparable sales. This is the default on most standard auto policies.
- Stated amount: You "state" a value and pay premium on it, but the policy typically pays the lesser of that amount or ACV. Many owners don't realize this until a claim.
- Agreed value: You and the insurer settle on a value when the policy is written, usually backed by an appraisal or documentation. After a covered total loss, that figure is what you receive, minus any deductible.
Stated amount coverage is the trap I see most often. An owner pays premium on a $165,000 figure, then learns the policy language caps the payout at market value. On a car with dealer-installed carbon packages and a bespoke Fuoriserie interior, the gap can be painful.
Why Depreciation Models Fail Maserati Owners
Standard ACV formulas lean on broad market data. They don't distinguish a limited-run GranTurismo Folgore from a high-mileage lease return. They also struggle with options. A Sonus Faber audio upgrade, a custom paint color, or a Trofeo package may be undervalued or ignored outright in an automated valuation.
Some models also behave strangely over time. Certain special editions hold value or appreciate, while volume models drop fast in their first few years. A depreciation model designed for the median vehicle can't capture that spread, and the owner absorbs the difference.
How Agreed Value Settlements Work During a Total Loss
With an agreed value policy, the conversation happens before the accident, not after. You'll typically provide a purchase invoice, window sticker, build sheet, or professional appraisal. The carrier accepts the figure, and you review it at each renewal.
If the car is totaled, there's no haggling over comparables. You receive the agreed amount, and depending on the policy, you may have the option to buy back the salvage. That matters for collectors who want to rebuild a rare car rather than walk away from it. Ask your agent to put the agreed figure on the declarations page so there's no ambiguity.
Maserati Approved Repair Networks and OEM Parts
The partial loss, not the total loss, is where most Maserati claims happen. Think about a deer strike on Route 16 near Conway or a parking garage scrape in downtown Portsmouth. The question becomes who fixes the car and with what parts.
Here's a New Hampshire nuance many owners miss. For vehicles older than two years or with more than 30,000 miles, insurers are permitted to specify aftermarket parts as long as they're deemed of "like kind and quality." A three-year-old Levante with 32,000 miles could fall squarely into that window. "Like kind and quality" is a judgment call, and you'd be surprised how much a non-OEM headlamp assembly or bumper cover can differ in fit, sensor calibration, and finish.
Modern Maseratis are packed with radar, cameras, and driver-assistance modules embedded in bumpers and windshields. An aftermarket cover that's a few millimeters off can throw off adaptive cruise or lane-keeping calibration. That creates a safety issue on top of a cosmetic one.
What to look for in policy language:
- OEM parts endorsement: Requires original manufacturer parts regardless of vehicle age or mileage. This is usually a modest premium increase, and it's well worth it on a Maserati.
- Choice of repair facility: Confirms you can use a Maserati-certified collision center rather than a carrier's preferred shop.
- Diminished value provisions: Some high-value policies address the loss in resale value after a significant repair. Standard policies rarely do.
- Rental or loaner equivalency: A comparable vehicle during repairs, since parts for Italian cars can take weeks to arrive.
Specialty carriers like Chubb and PURE often build OEM parts and shop choice into their base forms. Regional and national carriers may offer them as endorsements, or not at all.
Specialized Coverage for Transport and Storage
Many New Hampshire Maserati owners split their year. The car might live in a heated garage in Rye from May through October, then ship to Florida or sit in climate-controlled storage near Nashua through the winter. Each of those transitions carries risk that a standard auto policy may not address cleanly.
Transport services are a critical consideration for New Hampshire luxury vehicle owners given the state's climate and shipping needs. The insurance side gets far less attention than it should.
Enclosed Trailer Protection for Seasonal Relocation
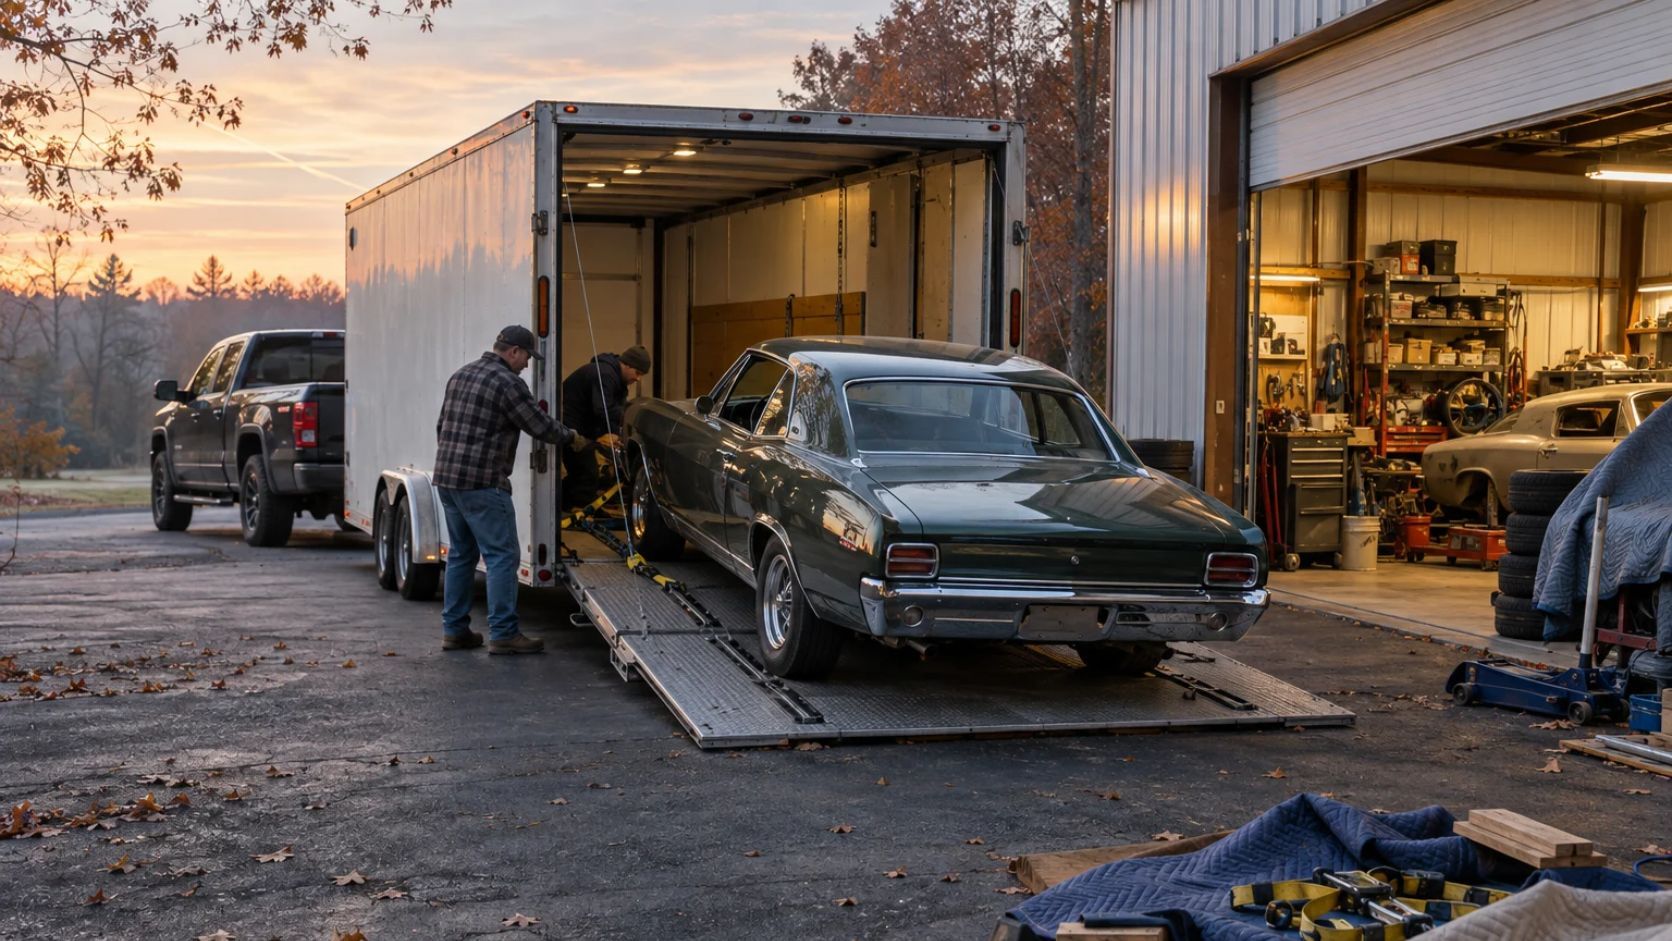
Open carriers expose your car to road debris, weather, and salt spray for 1,300-plus miles of I-95. Local providers such as Baier Transport in Seabrook offer white-glove enclosed shipping designed to protect exotic vehicles from salt and debris during transit. That's the right call for a Maserati.
The catch is that the transporter's cargo insurance is often limited per vehicle or per load, may carry its own deductible, and can exclude certain damage types. Before the car loads, ask for the carrier's certificate of insurance and check the per-vehicle limit against your agreed value. Then confirm your own policy covers the car while it's in a third party's custody. Some high-value auto forms explicitly extend comprehensive coverage during shipping. Others leave a gray area that only surfaces after a claim. Photograph every panel at pickup and delivery, with timestamps.
Lay-up Periods and Winter Storage Discounts
If your GranTurismo hibernates from Thanksgiving to Easter, you shouldn't be paying full liability and collision premiums for miles you aren't driving. Many carriers offer lay-up or storage provisions that suspend driving-related coverage while keeping comprehensive active.
Comprehensive should never come off. A stored car still faces fire, theft, a collapsed roof under a heavy snow load, frozen sprinkler pipes, or rodents chewing through wiring harnesses. That last one is a surprisingly common winter claim in rural barns across the Lakes Region. If you store the car at a facility rather than your own garage, confirm whether the facility's coverage is primary or excess. Then get the lay-up dates in writing so a spontaneous March drive on a dry day doesn't land you uninsured.
Choosing Optimal Liability and Physical Damage Limits
Physical damage coverage protects the car. Liability coverage protects everything else you own, and for families with $1.5 million homes, investment accounts, and business interests, that's where the real exposure lives.
A Maserati is a high-performance vehicle. If you cause a serious multi-car accident on I-93, plaintiffs' attorneys will look at the car you drove and assume deep pockets. Minimum or "typical" liability limits can be exhausted quickly in a serious injury case, leaving personal assets exposed.
Practical guidelines I'd suggest discussing with your agent:
- Set auto liability high enough to sit underneath your umbrella. Most umbrella policies require specific underlying auto limits. Mismatches create gaps where neither policy responds.
- Size the umbrella to your net worth and earning power, not to what feels "normal." Owners with significant assets often carry several million in excess liability.
- Don't skimp on uninsured and underinsured motorist coverage. Because New Hampshire doesn't mandate insurance for most drivers, UM/UIM protects you and your passengers when the at-fault driver can't pay.
- Match deductibles to your liquidity, not your ego. A higher collision deductible lowers premium, and for many affluent clients a $2,500 or $5,000 deductible makes sense because small claims aren't worth filing anyway.
- Review medical payments coverage for passengers, especially if grandchildren or guests ride along.
Physical damage limits should simply equal your agreed value, reviewed annually. If the car appreciates, or you add options, update the figure. Underinsuring a rising collectible is just as costly as overpaying on a depreciating one.
Comparing Standard vs. High-Value Maserati Policies
Not every Maserati needs a specialty policy. A leased Grecale driven daily might do fine on a strong standard form with the right endorsements. But as values climb and the car becomes part of a broader asset picture, the differences grow sharper.
| Feature | Standard Auto Policy | High-Value Specialty Policy |
|---|---|---|
| Total loss settlement | Actual cash value | Agreed value |
| Parts used | Aftermarket allowed (older/higher mileage) | OEM typically guaranteed |
| Repair shop | Carrier network often encouraged | Owner's choice, including certified shops |
| Transport coverage | Often unclear | Frequently addressed explicitly |
| Storage/lay-up | Limited or unavailable | Commonly offered |
| Diminished value | Rarely included | Available on some forms |
| Liability coordination | Separate from umbrella | Usually packaged with umbrella and home |
| Claims handling | High-volume adjusters | Dedicated high-value claims teams |
The best Maserati coverage in New Hampshire usually comes from a carrier that also writes your home, umbrella, and collections. Packaging creates consistent limits across policies, fewer gaps, and one claims relationship when something goes wrong.
Carrier fit varies. National carriers compete aggressively on price for newer, lower-value models. New England regional carriers often understand local weather risks well. Specialty carriers such as Chubb, PURE, and similar high-net-worth writers tend to shine on agreed value, OEM parts, and claims service. An independent agent can quote across all three tiers instead of steering you toward one company's product.
Common Questions About Insuring Your Maserati
Do I legally need car insurance for my Maserati in New Hampshire? Most drivers aren't required to carry it, but you must show financial responsibility after an at-fault crash. Practically, any lender or lessor will require full coverage, and going without on a car this valuable is a serious financial risk.
Is agreed value coverage more expensive? It can cost slightly more than standard ACV coverage, but the difference is often smaller than owners expect. The certainty of the settlement typically outweighs the added premium.
Can my insurer force me to use aftermarket parts? For cars older than two years or with over 30,000 miles, New Hampshire allows insurers to specify "like kind and quality" aftermarket parts. An OEM parts endorsement prevents that.
Will my policy cover the car while it's being shipped to Florida? It depends on the policy wording. Confirm with your agent before shipping, and check the transporter's cargo limit against your car's value.
Can I pause coverage while my car is stored for winter? Many carriers allow you to suspend driving coverages during a lay-up period. Keep comprehensive active to protect against fire, theft, and storage damage.
What happens if I miss a payment?
Under 2026 rules, insurers must give you a 10-day cure period before canceling for non-payment. Fix the issue right away rather than relying on that window.
Making the Right Choice for Your Maserati
The right policy for a Maserati isn't the cheapest quote that names the car correctly. It's the one that pays the agreed figure after a total loss and insists on factory parts installed by technicians who know the platform. It should also follow the car onto an enclosed trailer and stay sensible while the car sleeps through a Granite State winter. And the liability limits underneath it should protect the home, savings, and business you've spent decades building.
Most gaps only show up during a claim, which is the worst possible time to find them. Take one practical step this month. Pull your declarations page and check four things: the settlement type, the parts language, transport and storage provisions, and whether your auto limits line up with your umbrella.
Avery Insurance Agency has been advocating for New Hampshire families since 1899, and our consultative approach is built for exactly this kind of review. Reach out to Avery Insurance Agency for a coverage review that treats your Maserati as part of your whole asset picture, so you can enjoy the drive and sleep well at night.
ABOUT THE AUTHOR:
Tod O’Dowd, CIC, CAPI
I'm the President of Avery Insurance Agency, a family-owned independent agency serving individuals and businesses across New England and in 40+ states. With a hands-on, consultative approach to personal and commercial risk, I help clients — from high-net-worth homeowners and contractors to restaurant owners and property managers — find the right coverage without the guesswork of working with a single-carrier agent.
What Our Clients Say
Trusted by Families and Businesses for Over a Century
Trusted by New Hampshire Families and Businesses for Over a Century
Your Life. Protected.
Complete Personal Insurance for Individuals Who Expect More
One Agency. Every Coverage You Need. No Gaps, No Surprises.
Home Insurance
Your home is your most valuable asset. Avery’s home insurance protects your property, belongings, and liability so you can feel secure no matter what happens.
High-Value Home Insurance
Own a home valued over $2 million? Our Premier Client Services program provides coverage built around high-value properties and the unique risks they carry.
Auto Insurance
Whether you drive a daily commuter, a classic car, or a motorcycle, Avery finds the right auto coverage for your vehicle and your budget.
Boat & Watercraft Insurance
From small boats on New Hampshire’s lakes to luxury yachts, Avery provides watercraft insurance covering your vessel, passengers, and liability on the water.
Umbrella / Personal Liability Insurance
An umbrella policy adds an extra layer of liability protection above your home and auto coverage. One of the most cost-effective ways to protect your financial future.
Valuable Possessions Insurance
Jewelry, art, collectibles, and other high-value items need coverage beyond a standard homeowners policy. Avery insures your most prized possessions at full appraised value.
Protect Your Business & Livelihood
Commercial Insurance Solutions Designed for New England Businesses.
Comprehensive Commercial Coverage That Keeps Your Business Running
General Liability Insurance
Protect your business from third-party claims of bodily injury, property damage, and personal injury. General liability is the foundation of any solid business insurance program.
Commercial Property Insurance
Covers your building, equipment, inventory, and other physical assets against fire, theft, vandalism, and other covered losses. Keep your business protected from the unexpected.
Workers’ Compensation Insurance
Workers’ comp covers medical costs and lost wages when an employee is injured on the job. Avery helps businesses meet state compliance requirements and manage costs effectively.
Cyber Liability Insurance
Data breaches and cyberattacks are a growing risk for businesses of all sizes. Cyber liability covers response costs, legal fees, and customer notification expenses after a security incident.
Employment Practices Liability Insurance
Covers your business against employee claims of wrongful termination, discrimination, harassment, and related issues. Essential for any business with employees.
Commercial Auto Insurance
Whether a single truck or a full fleet, commercial auto insurance protects your business against accidents, damage, and liability on the road.
We Know Your Industry
Tailored Insurance Programs for the Industries That Drive New Hampshire
We Understand the Risks Your Industry Faces — and How to Manage Them
Contractors Insurance
From general contractors to specialty trades, Avery understands the unique liability and property exposures your business faces on every job site in New England. We build coverage programs that keep your crew and company protected.
Restaurants & Hospitality
Restaurants, hotels, and marinas face distinct risks — from slip-and-fall liability to liquor liability and food spoilage. Avery designs coverage programs for the specific needs of the hospitality industry.
Real Estate & Property
Whether you own a portfolio of investment properties or manage a condo association, Avery provides the right mix of property, liability, and management coverage to protect your real estate investments.
We Make It Simple
Getting Covered with Avery Is Easy
Step 01
Connect with an Avery Advisor
Call, email, or request a coverage online and we will respond the same business day.
Step 02
We Build Your Coverage Plan
We shop top-rated carriers, compare your options, and recommend the best fit for your needs.
Step 03
You Get Protected and Stay Protected
We place your coverage, review it annually, and advocate for you if you ever need to file a claim.
Let’s Clear Things Up
Got Questions? We’ve Got Answers.
Straight Answers From the Advisors Who Know This State Best
What does it mean that Avery is an independent insurance agency?
An independent agency like Avery is not tied to any single insurance company. We represent multiple top-rated carriers, which means we can shop the market on your behalf and recommend the coverage that truly fits your needs — not the one that benefits any single insurer.
This independence gives you access to more options and unbiased advice. Our advisors are compensated to serve your interests, not to push a specific product. That is a significant advantage over captive agents who can only offer one carrier’s policies.
How much does it cost to work with an Avery advisor?
There is no direct cost to you for working with an Avery advisor. Independent agents are compensated through commissions paid by the insurance carriers when a policy is placed. You receive expert guidance, market comparisons, and ongoing service at no extra charge.
In fact, many clients find that working with Avery saves them money. Our advisors know how to identify the right coverage levels so you are not paying for protection you do not need, and you are not left exposed where you do.
Does Avery help with claims?
Yes — and this is one of the most important things that sets Avery apart. When you have a claim, our in-house claims advisors go to work for you. We guide you through the process, communicate with the insurance company, and advocate for a fair and timely outcome.
Several of our team members hold professional claims designations, including AIC and AINS. We do not just help you file paperwork — we actively represent your interests to make sure you receive the full benefit your policy provides.
Where in New Hampshire does Avery provide coverage?
Avery serves clients throughout the state of New Hampshire from our offices in Wolfeboro and Portsmouth. Whether you live in the Lakes Region, the Seacoast, the White Mountains, or the Merrimack Valley, an Avery advisor is ready to help you find the right coverage.
Our advisors understand the specific risks that come with living and doing business in New Hampshire — from harsh winter weather to seasonal watercraft exposure. We apply that local knowledge to every coverage recommendation we make.
How does Avery handle high-value homes and assets?
Avery offers a dedicated Premier Client Services program for clients with homes valued over .5 million, significant investment portfolios, fine art collections, jewelry, yachts, and other complex assets. This program pairs you with a specialist who understands the unique risks of high-net-worth households.
Through carriers that specialize in high-value personal lines, we provide guaranteed replacement cost coverage, agreed value policies, and comprehensive risk management strategies. Your advisor will conduct a detailed review of your full asset portfolio to make sure nothing is overlooked or underinsured.
How often should I review my insurance coverage?
Avery recommends a full coverage review at least once a year. Major life events — buying a home, starting a business, adding a vehicle, getting married, or making significant home improvements — are all good triggers for an immediate review outside your annual cycle.
Insurance needs change over time, and policies that were right for you a few years ago may leave gaps today. Avery advisors proactively reach out to clients for annual reviews and keep up with changes in the insurance market that could affect your coverage or premium. Our goal is to make sure you are always protected and never paying for coverage that no longer fits.
Insurance Tips & News
Stay Informed with the Avery Blog
Practical Insurance Advice for New Hampshire Families and Business Owners
Contact Us
Portsmouth (HQ)
7 Islington St #102, Portsmouth, NH 03801
Phone Number: 603.766.3733
Wolfeboro
21 S Main Street, Wolfeboro, NH 03894
Phone Number: 603.569.2515